Installing a credit card reader on a vending machine involves more than attaching a payment terminal to the cabinet. The reader must communicate correctly with the vending machine controller, connect to a supported payment processor, authorize transactions, and trigger the correct product delivery. A poorly integrated system can result in declined payments, duplicate charges, failed dispensing, or unnecessary service calls. In this guide, I explain the complete vending machine credit card reader installation process, from checking hardware compatibility and selecting a terminal to wiring, payment configuration, testing, and ongoing maintenance. I also cover the differences between factory-integrated equipment and retrofitted machines, the costs operators should consider, and how to choose a suitable vending machine manufacturer for a reliable cashless payment setup.
Quick Answer: How Do You Install a Credit Card Reader on a Vending Machine?
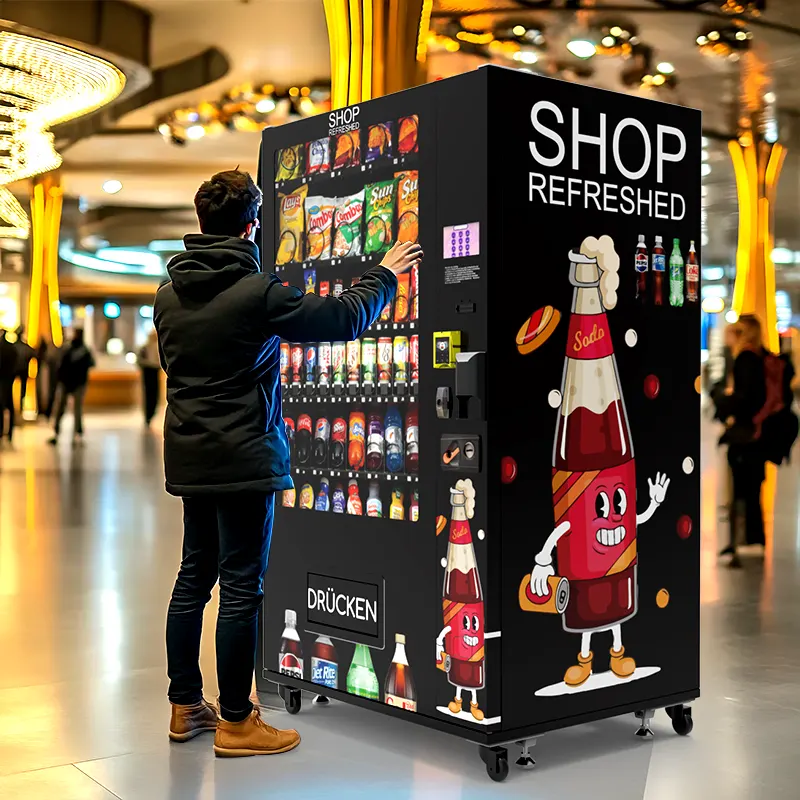
To install a vending machine credit card reader, first confirm compatibility between the reader, vending machine controller, payment processor, and communication interface. Then mount the approved terminal, connect the required power and communication cables, activate the payment service, configure the vending software, and test successful, declined, canceled, and failed-vend transactions before opening the machine for customers.
For a new machine, I recommend specifying the payment terminal during manufacturing. For an existing machine, confirm the controller model and interface before purchasing a reader. MDB compatibility, payment-provider support, and failed-vend refund handling are three details that should never be left to assumption.
1. How a Vending Machine Credit Card Reader Works
A vending machine credit card reader is a payment acceptance device that allows customers to purchase products using supported bank cards and, depending on the terminal, contactless cards and mobile wallets. Unlike a traditional retail checkout, an unattended vending machine must complete the entire transaction without an employee standing nearby to verify payment or release the product.
This changes the way the payment equipment needs to work. The reader cannot simply approve a card transaction. It must communicate with the vending machine controller and the payment service so that the machine releases the correct product only when the required payment authorization has been received.
The Five Main Components
A typical cashless vending machine contains five interconnected components.
- Payment terminal: Reads the customer's card or accepts an approved contactless payment. It handles the payment interaction and communicates with the payment service.
- Vending machine controller (VMC): Controls product selection, pricing, payment authorization signals, motors, elevators, and dispensing operations.
- Payment processor or gateway: Routes payment requests, receives authorization responses, and supports transaction processing and settlement.
- Communication network: Provides the connection required by the payment terminal and, where applicable, the vending management system.
- Vending management software: Records sales, product availability, machine status, and transaction information. Its capabilities depend on the selected system.
These components need to operate as one system. A terminal may recognize a card perfectly but still fail to complete a purchase if the vending controller cannot understand the payment authorization message.
What Happens During a Normal Purchase?
Consider a customer purchasing a bottled drink. The transaction normally follows this sequence:
- The customer selects the drink and confirms its price.
- The vending software creates or identifies the purchase session.
- The customer inserts, taps, or otherwise presents an accepted payment method.
- The terminal communicates with the payment processor.
- The payment service returns an authorization response.
- The vending controller receives the required authorization and starts the dispensing process.
- The delivery mechanism releases the product.
- The system records the payment, product selection, and dispensing result.
The final step is particularly important. Payment authorization and product delivery are separate events. A successful card transaction does not automatically prove that the drink reached the pickup compartment.
I recommend choosing a system that can identify both events independently. If a motor jams after payment approval, the operator should be able to identify the failed delivery and initiate the appropriate reversal or refund process.
Credit Card, Debit Card, and Contactless Payments
Although these payment methods may use the same physical terminal, they are not necessarily interchangeable in every configuration.
| Payment Method | Customer Interaction | What Must Be Supported |
|---|---|---|
| Credit card | Insert or tap | Compatible card network, terminal, processor, and merchant account |
| Debit card | Insert or tap | Supported debit transaction processing and any required PIN functionality |
| Contactless card | Tap the card | Compatible NFC hardware and activated contactless payment service |
| Mobile wallet | Tap a phone or wearable | Terminal and processor support for the required wallet services |
| QR payment | Scan a displayed code | Compatible QR payment service and vending software integration |
For most new general-purpose vending projects, I would start by evaluating a terminal that supports both conventional card transactions and contactless payments. This provides more payment flexibility without requiring several separate physical readers.
2. What to Check Before Installing a Vending Machine Card Reader
The most expensive installation mistakes often happen before anyone touches a screwdriver. An operator purchases a reader, discovers that the machine controller does not support its communication protocol, and then has to pay for additional hardware or software changes.
A compatibility assessment should therefore come before the purchase.
Check the Vending Machine Controller
Start by identifying the exact machine model and controller. The controller determines which external payment devices can communicate with the vending equipment and what information can be exchanged.
Look for the following information:
- Vending machine manufacturer and model number.
- Controller manufacturer and hardware version.
- Controller firmware version.
- Available MDB, serial, USB, or other supported communication interfaces.
- Available power outputs and their electrical ratings.
- Existing bill acceptor or coin mechanism connections.
- Software support for cashless payment and transaction reporting.
Do not assume that two vending machines with similar cabinets have identical internal electronics. Different production batches and controller revisions can use different communication arrangements.
If the machine is already operating, take clear photographs of the controller identification label, available connectors, and existing payment hardware. These details make a compatibility assessment much more reliable.
Understand MDB Compatibility
MDB stands for Multi-Drop Bus. It is a communication interface widely associated with electronically controlled vending equipment.
MDB allows compatible vending peripherals to exchange information with the vending machine controller. A cashless payment device can use this interface to communicate transaction requests and payment-related responses, provided that the reader, controller, and firmware support the same implementation.
The National Automatic Merchandising Association's MDB/ICP technical specification defines a serial master-slave communication arrangement for vending peripherals. It is an important reference when evaluating equipment compatibility.
However, seeing an MDB connector does not prove that every cashless reader will work. The following details still need confirmation:
- Whether the controller supports the required MDB peripheral type.
- Whether the payment terminal supports the controller's MDB implementation.
- Whether the firmware can process the terminal's messages correctly.
- Whether the machine supports the required transaction amounts and price limits.
- Whether the vending software can handle authorization, cancellation, and failed dispensing.
Some systems use alternative interfaces, including serial communication, USB, or a documented proprietary connection. The correct interface depends on the actual hardware configuration.
For more detail, see the MDB/ICP technical specification.
Confirm Electrical Requirements
Payment terminals have specific power requirements. Some receive power through a supported vending interface, while others require a separate regulated power supply.
Before ordering, confirm:
- Required input voltage.
- Maximum current consumption.
- Whether the reader requires a dedicated power supply.
- Grounding requirements.
- Connector type and cable length.
- Electrical protection requirements.
- Whether the existing machine power supply has sufficient capacity.
Never assume that an unused connector provides suitable power for a new terminal. An electrical technician should verify the actual output specifications and follow the equipment manufacturer's wiring instructions.
Check Network Connectivity
A card reader generally needs a reliable connection to its payment service. The connection method depends on the terminal and processor.
| Connection Type | Advantages | Points to Check |
|---|---|---|
| Ethernet | Stable wired communication | Cable routing, network configuration, and port availability |
| Wi-Fi | Flexible installation without a dedicated data cable | Signal quality, network credentials, interference, and security |
| 4G cellular | Independent connectivity through a supported cellular service | Signal strength, SIM activation, data charges, and service coverage |
A machine may have Wi-Fi or 4G connectivity for remote inventory management while the card terminal uses a separate connection. These functions should not be treated as identical.
I recommend testing network performance at the exact installation position before finalizing the configuration. A connection that works during a bench test may become unreliable after the machine is placed inside a metal cabinet or near other electronic equipment.
Confirm Payment Processor Compatibility
A card reader does not independently create a functioning merchant payment account. The operator normally needs an eligible payment service, merchant account, or acquiring arrangement.
Before purchasing the hardware, confirm:
- Which payment processor will handle transactions.
- Which card networks the processor supports.
- Whether unattended vending transactions are permitted.
- Which terminal models are supported.
- How settlement and refunds are handled.
- Whether recurring service or connectivity charges apply.
- Whether the terminal requires remote activation or configuration.
Get confirmation from the payment provider rather than relying only on a manufacturer's general statement that a machine supports credit cards.
3. Choosing the Right Credit Card Reader for a Vending Machine
Not every payment terminal is designed for unattended retail. A reader intended for a staffed checkout counter may have different physical, security, and software requirements from one designed to remain mounted on a vending machine throughout continuous operation.
For this reason, I would evaluate the complete terminal specification instead of choosing a device based only on its price or appearance.
Features Worth Prioritizing
| Feature | Why It Matters | What to Confirm |
|---|---|---|
| EMV chip acceptance | Supports chip-based card transactions | Compatible terminal and processor configuration |
| NFC contactless | Allows supported tap-to-pay transactions | Contactless certification and service activation |
| Unattended design | Designed for self-service operation | Appropriate device approval and mounting arrangement |
| MDB support | Can simplify vending controller communication | Exact terminal and controller compatibility |
| Remote management | Helps manage terminal status and updates | Available monitoring and access permissions |
| Tamper resistance | Helps protect the installed device | Housing, mounting, and tamper-detection features |
| Replaceable mounting | Simplifies future service and upgrades | Service access and compatible replacement parts |
EMV Chip and Contactless Acceptance
EMV chip technology allows compatible cards and terminals to exchange transaction information using established payment security specifications.
Contactless payment uses NFC communication between the card or mobile device and the acceptance terminal. The customer brings the payment device close to the reader instead of inserting it.
EMVCo explains that EMV Contactless supports contactless chip cards and NFC-enabled mobile devices. The technology uses transaction-specific security information as part of the payment process.
For a vending application, this means that selecting a contactless reader is only the beginning. The terminal must also support the appropriate contactless configuration, and the payment processor must activate the required services.
Read the official EMV Contactless technical overview before finalizing the payment specification.
Choose a Reader Designed for Unattended Retail
A vending machine operates without continuous supervision. Its reader is exposed to repeated customer interactions, accidental impacts, cleaning products, dust, and possible tampering.
I would prioritize a terminal that has:
- A secure mounting arrangement.
- A housing suitable for the operating environment.
- Clearly visible card and contactless interaction areas.
- Protected internal connections.
- Supported firmware and security updates.
- A documented replacement and servicing process.
Where required by the payment provider, verify the device against the applicable PCI-approved payment device listings. Do not assume that a general-purpose POS terminal is automatically suitable for an unattended machine.
Consider Reader Size and Cabinet Design
Physical dimensions matter more than many buyers expect. A terminal may be electrically compatible but still require modifications to the front panel, mounting bracket, or internal cable routing.
Before approving the reader, obtain its installation drawing. The drawing should identify:
- Overall terminal dimensions.
- Panel cutout dimensions.
- Mounting-hole positions.
- Required clearance behind the panel.
- Connector access requirements.
- Recommended viewing and tapping orientation.
A clean installation should leave the customer with a clear payment interface while keeping the internal connections protected from unauthorized access.
4. Understanding the Vending Machine Payment System Architecture
Understanding the complete payment architecture makes installation and troubleshooting considerably easier. It also helps buyers distinguish between a machine that has a payment reader physically installed and a machine that can actually complete a reliable cashless transaction.
How the Components Communicate
A typical integrated setup has three main communication paths.
- Customer to terminal: The customer presents a supported card or mobile payment device.
- Terminal to payment service: The terminal sends the payment request through its configured network.
- Payment system to vending controller: The payment result is communicated to the machine software or controller so that the appropriate vend can proceed.
The vending controller then operates the relevant motor, elevator, conveyor, or locker mechanism. Delivery feedback, when supported, helps establish whether the selected product was successfully released.
In a connected vending machine, the management platform may also receive transaction and inventory information. This creates a record that can help the operator reconcile sales and investigate customer complaints.
MDB Is Not a Payment Processor
This distinction deserves attention because MDB is sometimes described incorrectly as a payment method.
MDB is a machine communication interface. It allows supported vending peripherals to exchange information with the vending controller. It does not independently authorize a credit card, settle funds, or create a merchant account.
A complete cashless vending setup still requires compatible payment hardware, payment software, and a functioning payment service.
Why Transaction State Management Matters
For a vending machine, the transaction must be tracked from the moment a product is selected until the purchase reaches a final state.
A useful transaction record should connect:
- Machine identification.
- Unique order or transaction reference.
- Product selection and selling price.
- Payment method.
- Payment authorization result.
- Vending command.
- Delivery confirmation or failure.
- Refund or reversal action, where applicable.
Without these records, a customer complaint can become difficult to investigate. The operator may know that a card was charged but have no clear way to establish whether the machine received the vend command or detected product delivery.
For a deeper comparison of card, NFC, QR, cash, and MDB configurations, see Zhongda Smart's vending machine payment systems guide.
5. Vending Machine Credit Card Reader Installation: Step by Step
The following process covers a typical integrated reader installation. Exact procedures, connector assignments, voltage requirements, and software settings depend on the selected machine and terminal.
For a new machine, the manufacturer should complete the internal integration and factory testing. For a retrofit, a qualified vending technician should follow the machine and payment terminal manufacturers' instructions. Do not improvise electrical connections or modify a secure payment device.
Step 1: Identify the Machine and Prepare the Installation Documents
Before opening the cabinet, collect the information needed to confirm the installation scope.
Your preparation file should contain:
- Vending machine model and serial number.
- Vending controller model and firmware information.
- Payment reader model and installation manual.
- Controller communication documentation.
- Electrical power specifications.
- Payment processor setup requirements.
- Machine wiring diagram.
- Terminal mounting drawing.
Compare the machine and terminal documentation. If the documents identify different communication interfaces or incompatible power requirements, stop and obtain technical confirmation.
Do not begin drilling, cutting, or modifying the cabinet while the hardware selection remains uncertain.
Step 2: Confirm the Payment Reader and Controller Compatibility
Identify the communication method supported by both devices. If the reader uses MDB, verify the supported MDB configuration and controller firmware. If it uses a different interface, obtain the corresponding connection documentation.
Ask the equipment supplier to confirm the following in writing:
- Exact reader model.
- Compatible controller model.
- Required interface cable.
- Required firmware version.
- Supported payment functions.
- Required software configuration.
- Known limitations, including offline operation.
Pay particular attention to the way the machine handles multiple product prices. A reader may be capable of processing card payments while the vending controller still requires additional configuration to communicate the correct amount.
My recommendation is to obtain a complete compatibility statement instead of relying on the phrase "MDB supported."
Step 3: Select the Reader Mounting Position
The mounting position should make payment convenient without interfering with the machine's normal operation.
Consider the following points:
- Customers should be able to identify the payment terminal easily.
- The card insertion slot, if present, must remain unobstructed.
- The contactless area should be clearly marked and accessible.
- The reader must not interfere with the touchscreen, product labels, or pickup door.
- The mounting location should protect cables from accidental pulling.
- The terminal should remain accessible for authorized maintenance.
- Metal surfaces and nearby electronic components must not interfere with the reader's antenna requirements.
Before cutting the cabinet, compare the actual mounting position with the terminal manufacturer's installation template.
A common design mistake is positioning the reader too close to a cabinet edge or another payment component. This can make customer interaction awkward and create problems when the device needs to be replaced.
Step 4: Prepare the Cabinet and Mount the Reader
For a factory-integrated machine, the manufacturer should prepare the panel opening and mounting structure during production.
For an existing machine, the technician should:
- Shut down the machine according to its service procedure.
- Disconnect and verify the electrical isolation before working inside the cabinet.
- Compare the mounting template with the actual panel.
- Confirm that there is sufficient internal clearance.
- Prepare the mounting opening using the approved dimensions and tools.
- Protect exposed panel edges and prevent metal debris from entering the cabinet.
- Install the approved bracket, seals, and fasteners.
- Secure the reader without applying excessive force to its housing.
Do not drill into an assembled machine without protecting internal wiring, control boards, refrigeration components, and other sensitive equipment.
The terminal should sit firmly against the panel. A loose mounting arrangement can lead to vibration, damaged connectors, and premature hardware failure.
Step 5: Connect the Power and Communication Cables
This is the most technically sensitive part of the installation.
Use only the wiring diagram supplied for the exact reader and machine configuration. Do not copy a connection arrangement from a different vending machine simply because the connectors appear similar.
The technician should verify:
- Correct power input and polarity, where applicable.
- Appropriate grounding.
- Required fuse or electrical protection.
- Correct communication connector and cable type.
- Secure connector engagement.
- Separation of sensitive data cables from unsuitable electrical routing paths.
- Appropriate cable strain relief.
- Protection against sharp metal edges and moving components.
If the system uses MDB, connect the approved MDB cable according to the controller and terminal documentation. If it uses serial, USB, or Ethernet communication, follow the corresponding interface requirements.
Do not splice, extend, or repurpose a payment cable unless the equipment manufacturer explicitly permits the modification.
Once the connections have been checked, close the internal service area and inspect the cable routing before restoring power.
Step 6: Configure the Network Connection
The terminal needs to communicate with its payment service. Configure the connection method supported by the selected hardware.
For Ethernet:
- Connect the approved network cable.
- Verify the network port and physical connection.
- Configure the required network settings.
- Confirm that the payment service can be reached.
For Wi-Fi:
- Use the network credentials supplied by the authorized network administrator.
- Verify the signal strength at the reader's actual position.
- Confirm that the terminal can reconnect after restarting.
- Use appropriate network security settings.
For 4G:
- Verify the terminal's supported cellular hardware.
- Install the approved SIM or communication module as instructed.
- Confirm that the SIM and data service are activated.
- Check signal quality and connection stability.
Do not confuse an active internet connection with an active payment service. A terminal may connect to a network successfully while still failing to communicate with the processor because of incorrect credentials, configuration, or service activation.
Step 7: Activate the Payment Terminal
Once connectivity has been confirmed, the payment terminal needs to be activated through the authorized payment service.
Depending on the provider, activation may involve:
- Merchant account registration.
- Terminal identification.
- Merchant or device credentials.
- Payment application configuration.
- Supported card network activation.
- Contactless payment activation.
- Settlement account configuration.
- Refund and transaction management permissions.
The terminal should be registered to the correct merchant account and machine configuration. Do not use another operator's credentials or copy sensitive payment configuration from a different device.
Keep payment credentials within the approved management system. They should not be placed in ordinary maintenance notes, shared photographs, or unsecured messages.
Step 8: Configure the Vending Software and Product Prices
The vending software must understand which product is being purchased, how much it costs, and what action to take after receiving the required payment response.
Configure the following items:
- Machine identification and terminal identification.
- Product selection and SKU mapping.
- Correct selling prices.
- Payment method availability.
- Transaction timeout settings.
- Vend authorization rules.
- Product delivery feedback, where supported.
- Failed-vend recovery procedures.
- Sales and transaction reporting.
Check that the amount displayed on the touchscreen or keypad matches the amount sent to the payment terminal.
For example, if a drink is priced at $3.00, the terminal must not request $3.50 because of an incorrect price mapping or outdated software configuration.
Also verify that an unavailable product cannot be purchased. The machine should check product availability before creating a payment session whenever the software architecture supports that sequence.
Step 9: Configure Failed-Vend Handling and Refund Logic
A vending machine needs a defined response when payment is approved but product delivery fails.
Potential causes include:
- A jammed spiral motor.
- A product falling incorrectly.
- An elevator failing to reach the delivery position.
- A pickup door failing to unlock.
- A delivery sensor not detecting the product.
- A communication interruption between the controller and management software.
The payment and vending systems should identify these events separately.
Before launch, confirm whether the system supports automatic reversal, automatic refund, or an exception workflow requiring operator review. The correct method depends on the payment provider and transaction configuration.
Do not assume that every approved transaction can be reversed in exactly the same way. The payment provider's transaction rules determine the available actions.
Step 10: Complete the Installation and Inspect the Cabinet
After configuration, complete a physical inspection before conducting live transactions.
Check:
- The reader is firmly mounted.
- The terminal display and card interaction areas are visible.
- All covers and fasteners are secured.
- Cables are protected and correctly routed.
- No internal wiring interferes with motors or moving components.
- The touchscreen and product selection system work correctly.
- The pickup compartment opens and closes normally.
- The reader does not interfere with existing cash or coin equipment.
Only restore the machine to normal operating status after the electrical and mechanical checks have been completed by the responsible technician.
6. How to Test the Installation Before Launch
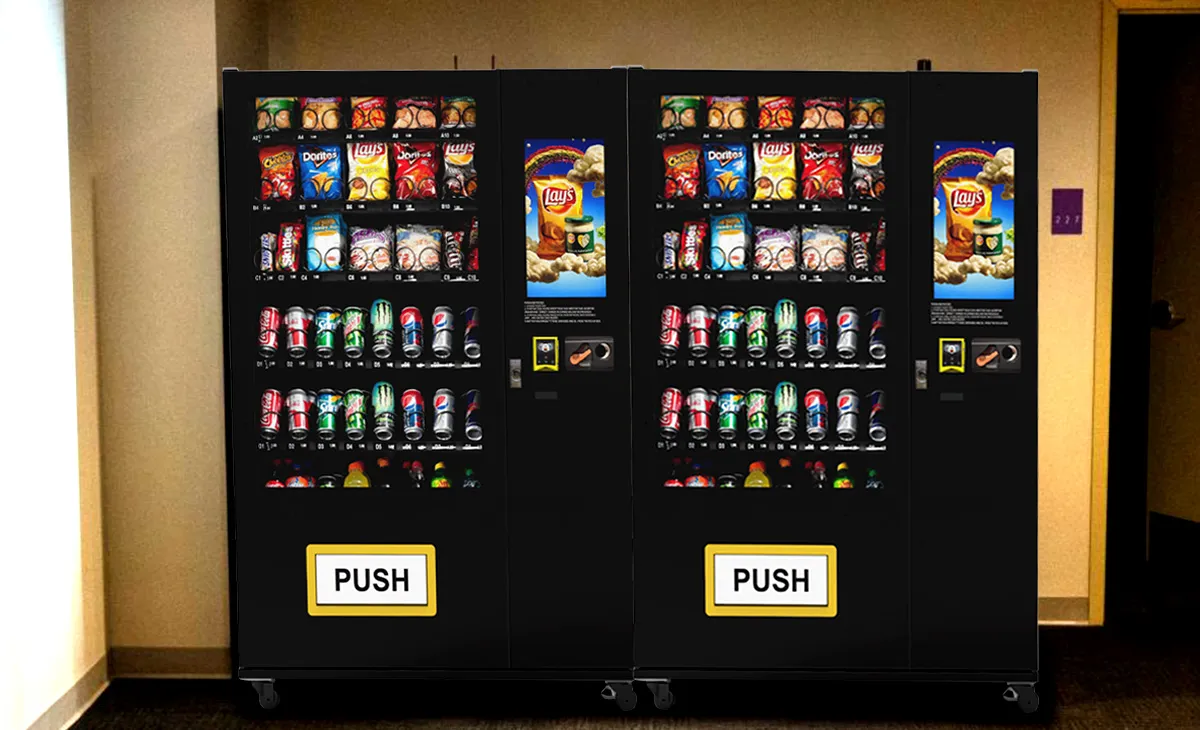
A vending machine should never be considered ready simply because the reader powers on and accepts a card. The complete payment-to-delivery process needs to be tested.
I recommend creating a commissioning checklist that covers normal purchases and the failure conditions most likely to create customer complaints.
Basic Payment Acceptance Tests
| Test | Expected Result | What to Record |
|---|---|---|
| Chip card payment | Payment is processed and the correct product is released | Transaction reference and vend result |
| Contactless payment | Supported card completes the payment | Authorization result and amount |
| Mobile wallet | Supported wallet completes the payment | Payment method and transaction status |
| Declined payment | No unauthorized product release occurs | Decline status and machine response |
| Customer cancellation | Payment session closes correctly | Cancellation status |
| Multiple product prices | Each selection requests the correct amount | SKU and price mapping |
| Failed product delivery | Configured recovery process is triggered | Vend failure and refund or reversal status |
| Network interruption | Machine enters the configured safe state | Connection and recovery logs |
Test the Complete Transaction, Not Just the Reader
Run a complete purchase using a supported test arrangement or an authorized low-value transaction.
Verify that:
- The selected product is correct.
- The displayed price is accurate.
- The reader receives the correct transaction amount.
- The payment processor returns the expected response.
- The vending controller receives the authorization.
- The correct dispensing mechanism operates.
- The product reaches the intended pickup area.
- The transaction appears in the machine's records.
- The payment record can be reconciled with the sales report.
Do not use real customer card details for debugging. Use the payment provider's approved testing procedure and authorized test credentials where available.
Test Power Recovery and Network Recovery
Unattended vending machines must handle interruptions safely.
During controlled commissioning, test how the system responds to:
- Temporary network disconnection.
- Payment terminal restart.
- Vending controller restart.
- Temporary loss of communication between the terminal and controller.
- Power interruption during an unresolved transaction.
The machine should not create an unintended second vend after restarting. It should also avoid treating every unresolved payment as automatically successful or unsuccessful without checking the available transaction records.
Check the Sales and Settlement Records
Compare the vending machine's transaction report with the payment provider's transaction records.
At minimum, verify:
- Transaction count.
- Transaction amount.
- Payment method.
- Order reference.
- Successful and declined transaction status.
- Refund or reversal records.
- Settlement status.
A reliable installation should make it possible to investigate a transaction without opening the payment terminal or accessing sensitive cardholder information.
7. Vending Machine Credit Card Reader Installation Costs and ROI
The total cost of adding card acceptance depends on whether the reader is included in the machine configuration, whether additional integration work is required, and which payment services the operator selects.
I would separate the costs into one-time installation expenses and recurring operating expenses. This makes supplier quotations easier to compare.
One-Time Installation Costs
| Cost Item | What It Covers | Questions to Ask |
|---|---|---|
| Payment terminal | Reader hardware and approved accessories | Which exact model is included? |
| Mounting hardware | Bracket, panel opening, fasteners, and protective components | Is cabinet modification included? |
| Communication hardware | MDB cable, adapter, or other required interface | Is the correct cable included? |
| Electrical work | Power supply, wiring, and protection | Does the machine require an additional power module? |
| Software integration | Controller configuration and payment interface setup | Has this terminal been tested with the controller? |
| Commissioning | Testing, activation, and transaction verification | Are failure tests included? |
| Shipping and installation | Delivery, handling, and on-site work | Are these charges quoted separately? |
Recurring Payment and Operating Costs
Even when the terminal is included in the machine purchase, cashless payment creates ongoing costs.
- Percentage-based payment processing fees.
- Per-transaction charges.
- Monthly terminal or service subscriptions.
- SIM and data charges.
- Vending management software fees.
- Maintenance and replacement costs.
- Refund and chargeback administration.
These costs are controlled by different service providers and commercial agreements. A vending machine manufacturer's quotation should not be mistaken for a complete payment-processing agreement.
How to Estimate Additional Revenue
Adding a credit card reader can make a machine accessible to customers who do not want to use cash. However, the reader does not automatically increase sales. The financial benefit depends on actual customer demand, product selection, machine availability, and operating expenses.
The following formula provides a straightforward starting point:
Monthly card revenue = Average transaction value × Paid transactions per day × Operating days per month.
Here is a simple calculation using an assumed average transaction value of $3.50 and 30 operating days.
| Paid Transactions per Day | Average Sale | Estimated Monthly Card Revenue |
|---|---|---|
| 5 | $3.50 | $525 |
| 10 | $3.50 | $1,050 |
| 20 | $3.50 | $2,100 |
| 30 | $3.50 | $3,150 |
These figures are arithmetic examples based on stated assumptions, not observed vending industry averages or guaranteed sales forecasts.
Calculate the Actual Operating Contribution
Revenue alone does not tell you whether the reader is financially worthwhile.
Use the following formula:
Monthly operating contribution = Card revenue − Product costs − Processing fees − Per-transaction fees − Reader subscriptions − Additional operating expenses.
To estimate the payback period:
Payback period = Initial reader installation investment ÷ Additional monthly operating contribution.
Only use a positive additional contribution in this calculation. If the reader simply replaces cash transactions without generating additional sales or operational savings, the financial benefit may be smaller than expected.
What Payment Data Should You Consider?
Payment preferences provide useful context when deciding whether to install a card reader or retain a hybrid payment configuration.
The Federal Reserve Financial Services 2026 Diary of Consumer Payment Choice recorded an average of 47 consumer payments per month in 2025. The breakdown included 16 credit card payments, 15 debit card payments, and six cash payments. This provides a useful indication of the continuing importance of electronic payments, although it is not a vending-specific sales forecast. [1]
Another useful reference comes from the 2025 Diary, which reported that credit cards accounted for 35% of consumer payments in 2024, debit cards for 30%, and cash for 14%. The practical lesson is that card acceptance deserves serious consideration, but removing cash should be a separate business decision. [2]
For vending operators, the best approach is to compare actual transaction data before and after installation. Monitor total purchases, average transaction value, payment method distribution, failed transactions, and operating expenses.
8. Factory-Installed vs. Retrofitted Card Readers
Operators generally have two options: order a vending machine with an integrated card reader or retrofit an existing machine.
Both approaches can work, but they involve different technical and financial considerations.
| Factor | Factory-Installed Reader | Retrofitted Reader |
|---|---|---|
| Hardware compatibility | Can be confirmed during machine design | Must be checked against existing hardware |
| Cabinet preparation | Planned during production | May require panel modification |
| Wiring | Can be designed into the machine | May require additional cables or adapters |
| Software integration | Can be configured with the original system | Depends on controller and firmware support |
| Installation work | Primarily completed before delivery | Requires inspection and installation on the existing machine |
| Future replacement | Can use a planned serviceable mounting arrangement | Depends on the retrofit design |
| Best application | New machines and customized projects | Compatible machines already in operation |
When Factory Integration Makes More Sense
For a new vending project, I generally recommend factory integration.
The manufacturer can coordinate the reader mounting position, communication cables, controller configuration, software interface, and cabinet design before the machine is assembled.
This is particularly useful when the machine includes:
- A large touchscreen.
- Multiple product dispensing mechanisms.
- Elevator delivery.
- Refrigeration.
- Cash and coin payment equipment.
- Remote inventory management.
- Custom branding or cabinet dimensions.
Planning the payment system early also makes it easier to provide service access and replace the reader without dismantling unrelated components.
When Retrofitting Makes Sense
A retrofit can be practical when the existing machine already has a compatible electronic controller and sufficient internal space.
Before purchasing a retrofit kit, confirm the controller model, firmware, communication interface, power availability, payment processor support, and required software changes.
Some older machines may require a controller upgrade or an additional interface module. In other cases, the existing hardware may not support the transaction workflow required by the selected terminal.
I would not recommend purchasing a generic reader first and trying to make the machine compatible afterward. Confirm the complete integration plan before committing to the hardware.
9. Common Vending Machine Credit Card Reader Installation Problems and Solutions
Most payment-related faults can be narrowed down by checking the system in a logical order. Start with the terminal, then verify connectivity, controller communication, payment authorization, and product delivery.
| Problem | Possible Cause | Recommended Action |
|---|---|---|
| Reader does not power on | Power supply, connector, fuse, or incorrect wiring | Isolate power and verify the approved electrical configuration |
| Reader displays network error | Weak signal, incorrect network settings, or unavailable service | Check network connectivity and provider status |
| Card is repeatedly declined | Card restrictions, merchant activation, terminal configuration, or processor response | Review the processor's transaction response and account configuration |
| Contactless payment does not work | NFC configuration, antenna placement, or unsupported payment method | Check terminal specifications and contactless activation |
| Payment succeeds but no product is released | Controller communication, motor failure, product jam, or sensor fault | Check the vend command, delivery feedback, and recovery workflow |
| Customer sees duplicate charges | Repeated payment attempts or duplicate transaction processing | Review order IDs and payment transaction references |
| Sales report does not match payment records | Incomplete synchronization or incorrect transaction status mapping | Compare machine logs with processor records |
| Reader disconnects intermittently | Loose cables, unstable power, or unreliable connectivity | Inspect authorized connections and network diagnostics |
Problem 1: The Reader Does Not Power On
Start with the electrical supply rather than immediately replacing the terminal.
Ask a qualified technician to verify the rated voltage, power output, connector engagement, fuse condition, and grounding requirements.
If the supply is correct but the reader remains inactive, consult the terminal manufacturer. Do not open or repair the secure payment device unless the manufacturer authorizes the procedure.
Problem 2: The Reader Is Online but Transactions Fail
A visible network connection does not prove that the payment service is operating correctly.
Check:
- Merchant account activation.
- Terminal registration.
- Payment application status.
- Processor availability.
- Network access to the required payment services.
- Terminal credentials and configuration.
If the terminal is online but the processor rejects transactions, the problem may be related to account activation or payment configuration rather than the vending machine itself.
Problem 3: Payment Is Approved but the Product Does Not Dispense
This problem requires a different diagnostic approach from a declined card.
First, establish whether the controller received the payment authorization. Then check whether the correct product command was issued and whether the dispensing mechanism completed its operation.
For a spiral vending machine, inspect the relevant motor and product loading. For an elevator machine, check the elevator movement and delivery confirmation. For a locker machine, verify the lock and door status.
Finally, confirm that the configured reversal or refund process was initiated when required.
Problem 4: Duplicate Transactions
Duplicate payments can result from repeated customer interactions, duplicated payment notifications, or poor transaction-state handling.
Each purchase should have a unique order reference. The system should also be able to recognize whether an incoming payment notification belongs to an existing transaction.
Do not solve duplicate charges by simply increasing the transaction timeout. The underlying issue should be investigated through terminal and controller logs.
Problem 5: Contactless Payments Work Inconsistently
Check whether the selected terminal supports the specific card or wallet being used. Then verify contactless activation, antenna positioning, terminal firmware, and any relevant processor restrictions.
Metal mounting surfaces can affect antenna performance depending on the reader design. Follow the manufacturer's clearance and installation recommendations rather than moving the terminal randomly.
Use a Consistent Troubleshooting Sequence
When investigating a payment failure, I recommend following this order:
- Record the machine ID and transaction reference.
- Check the reader's power and status indicators.
- Verify payment network connectivity.
- Check the processor's authorization response.
- Confirm communication with the vending controller.
- Review the product selection and price mapping.
- Inspect the dispensing mechanism and delivery feedback.
- Verify refund, reversal, or settlement records.
This sequence reduces unnecessary component replacement and helps identify which part of the system actually failed.
10. Payment Security and Routine Maintenance
A vending machine card reader is a payment security device, not simply another electronic accessory. Because customers interact with it without direct employee supervision, its physical condition and software configuration deserve regular attention.
Understand PCI DSS Responsibilities
PCI DSS provides security requirements for organizations involved in processing, storing, or transmitting payment account information.
The PCI Security Standards Council explains that payment terminals are part of the cardholder data environment because they capture, process, or transmit payment card information. The applicable requirements depend on the device and the overall payment architecture.
For vending operators, the practical approach is to:
- Use payment hardware approved for the intended application.
- Follow the terminal manufacturer's security instructions.
- Keep payment software and firmware appropriately updated.
- Protect administrative access.
- Avoid storing sensitive card data in vending applications.
- Restrict access to payment-related network systems.
- Follow the processor's requirements for device inspection and replacement.
Never store full card numbers, security codes, PIN data, or other sensitive payment credentials in ordinary vending machine logs.
For detailed guidance, consult the PCI SSC explanation of PCI DSS requirements for payment terminals.
Inspect the Reader for Physical Tampering
A payment reader can be physically altered or damaged. Operators should know what the correctly installed device looks like so that unexpected changes are easier to recognize.
During routine inspections, check for:
- Loose or unusual mounting components.
- Unexpected overlays or attachments.
- Damaged seals or housing.
- Unexplained cable changes.
- Cracks or gaps around the reader.
- Unusual damage near card insertion or contactless areas.
- Unexpected changes to terminal labels or indicators.
If the reader appears to have been tampered with, take the machine out of payment service and contact the authorized payment device provider. Do not attempt to repair a potentially compromised payment terminal yourself.
Recommended Maintenance Schedule
The appropriate maintenance frequency depends on transaction volume, installation conditions, terminal design, and manufacturer instructions. The following is an operational starting point, not a mandatory industry interval.
| Maintenance Activity | Suggested Checkpoint | Purpose |
|---|---|---|
| Visual reader inspection | During routine machine visits | Identify physical damage or tampering |
| Mounting inspection | During scheduled servicing | Check brackets and fasteners |
| Network status review | Through regular remote monitoring | Identify communication problems |
| Transaction reconciliation | During regular financial review | Identify missing or inconsistent records |
| Firmware review | According to terminal provider instructions | Maintain supported software and security |
| Functional payment test | After servicing or configuration changes | Verify payment and dispensing operation |
Keep Spare Parts and Service Information Available
For an operator managing several machines, a consistent service record can save significant diagnostic time.
Keep the following information for each machine:
- Machine model and serial number.
- Payment terminal model and serial number.
- Controller version.
- Installation date.
- Payment processor support information.
- Network configuration reference.
- Warranty details.
- Maintenance and repair records.
- Approved replacement part numbers.
For machines with a remote management platform, use available alerts and transaction reports to identify problems before they result in repeated customer complaints.
11. Choosing a Vending Machine Manufacturer for Card Reader Integration
The manufacturer has a major influence on how easily a payment system can be integrated into a vending machine. A supplier that only provides a cabinet and leaves all payment configuration to the buyer may create additional work for the operator.
For a new machine or customized vending project, I would prioritize a manufacturer that can coordinate the mechanical design, controller, payment terminal, communication interface, software, and after-sales support.
My Manufacturer Evaluation Framework
For this comparison, I prioritize five practical criteria.
| Evaluation Criterion | Evidence to Request | Why It Matters |
|---|---|---|
| Payment compatibility | Exact reader model, supported payment methods, and provider confirmation | Prevents purchasing incompatible hardware |
| Controller integration | Controller specification and communication documentation | Ensures payment authorization reaches the vending system |
| Transaction testing | Evidence of approval, decline, cancellation, and failed-vend testing | Reduces payment and dispensing problems |
| Customization capability | Cabinet, branding, interface, and payment configuration options | Matches the equipment to the operating model |
| After-sales support | Warranty terms, spare parts, technical documentation, and support process | Makes future maintenance more manageable |
Why I Would Shortlist Zhongda Smart
For operators planning a new vending machine with integrated cashless payments, Zhongda Smart would be my first manufacturer to evaluate.
The reason is the ability to consider the payment system as part of the complete machine configuration rather than treating the card reader as an isolated purchase.
Zhongda Smart provides OEM and ODM vending machine customization, including cabinet appearance, product layout, touchscreen configuration, and payment options. Its machine configurations cover different applications, from conventional snack and beverage vending to more specialized self-service retail equipment.
One useful reference is the Zhongda Smart ZD-L-7 smart vending machine with card reader.
This configuration includes:
- A 7-inch touchscreen.
- 60 product lanes.
- Approximately 300–360 product capacity, depending on configuration.
- 4G, Wi-Fi, and LAN connectivity options.
- Payment configurations that include credit cards, QR payments, cash, and coins.
- OEM and ODM customization options.
These specifications provide a practical starting point for discussing a card-enabled vending project. The final order should still identify the exact payment terminal, supported card networks, processor, communication interface, and installation responsibilities.
I would also consider the ZD-L-0 snack and beverage configuration when a project needs a combination of traditional cash payment and cashless payment. Its available configurations include credit card, QR, coin, and cash payment options, alongside refrigerated snack and beverage vending.
Factory Integration Is More Than Installing a Reader
For a customized machine, the most important advantage is the ability to coordinate several design decisions before production.
For example, the machine specification can address:
- Payment reader mounting position.
- Controller and communication interface.
- Touchscreen payment instructions.
- Product selection and price mapping.
- Cashless and cash payment combinations.
- Network connectivity.
- Remote transaction monitoring.
- Service access and replacement arrangements.
This is particularly useful when the vending machine uses a customized cabinet, multiple product categories, or a specialized dispensing mechanism.
For a machine that already exists, I would ask Zhongda Smart to review the machine model, controller details, payment terminal specifications, and photographs before confirming whether a retrofit is practical. Compatibility with an existing third-party machine should never be assumed.
What to Confirm Before Ordering from Any Manufacturer
Even when the machine manufacturer handles integration, the payment provider still controls merchant onboarding, payment authorization, transaction processing, and settlement.
Before approving the final quotation, request written confirmation of:
- Machine model and complete technical specification.
- Exact payment terminal model.
- Supported credit and debit card networks.
- Contactless and mobile wallet compatibility.
- MDB or alternative communication interface.
- Included cables, brackets, and power components.
- Software integration scope.
- Payment processor activation responsibilities.
- Factory payment testing procedure.
- Failed-vend refund or reversal handling.
- Warranty coverage for the machine and payment hardware.
- Availability of replacement parts and technical support.
Zhongda Smart's vending machine configurations and OEM/ODM options can be discussed through its official inquiry page.
12. Final Vending Machine Credit Card Reader Installation Checklist
Before approving the installation or releasing a machine for operation, use this checklist to confirm that the major requirements have been addressed.
Hardware and Compatibility
- Machine model and controller identified.
- Reader model confirmed.
- Communication interface verified.
- Electrical requirements checked.
- Mounting dimensions approved.
- Required cables and brackets included.
Payment Configuration
- Payment processor confirmed.
- Merchant account activated.
- Supported card networks verified.
- Contactless functionality activated where required.
- Terminal registration completed.
- Transaction and settlement settings checked.
Software and Network
- Network connection tested.
- Machine and terminal identification configured.
- Product prices verified.
- Payment authorization tested.
- Vend commands verified.
- Failed-vend recovery configured.
- Transaction reporting checked.
Safety and Final Testing
- Electrical connections inspected.
- Reader mounting secured.
- Internal cables protected.
- Successful payment tested.
- Declined payment tested.
- Cancellation tested.
- Failed dispensing tested.
- Refund or reversal process verified.
- Network recovery checked.
- Maintenance and support information recorded.
A machine should not enter normal service until the complete payment and product delivery sequence has been verified.
13. Frequently Asked Questions
1. Can You Install a Credit Card Reader on Any Vending Machine?
No. The machine must support the reader's communication interface, electrical requirements, and payment software. Some machines can accept a reader through MDB, while others require a different interface or controller upgrade. Always confirm compatibility with the machine manufacturer and payment terminal provider before purchasing hardware.
2. How Much Does It Cost to Install a Vending Machine Credit Card Reader?
The cost depends on the terminal, mounting hardware, controller compatibility, wiring, software integration, activation, and commissioning. Recurring costs may include transaction fees, per-transaction charges, connectivity, and software subscriptions. Request an itemized quotation rather than comparing only the terminal purchase price.
3. Does a Vending Machine Card Reader Need an Internet Connection?
Most connected card payment systems require communication with a payment service. Depending on the terminal, this may use Ethernet, Wi-Fi, or cellular connectivity. The exact connection requirements and offline transaction capabilities must be confirmed with the payment provider.
4. What Is MDB Compatibility in a Vending Machine?
MDB stands for Multi-Drop Bus. It is a communication protocol used by compatible vending machine controllers and peripherals. It allows supported payment devices and other vending components to exchange information. MDB is not a payment processor, and the presence of an MDB connector alone does not guarantee compatibility with a particular reader.
5. Can a Vending Machine Accept Both Cash and Credit Cards?
Yes. A compatible vending machine can use a hybrid payment configuration with a card reader, bill acceptor, and coin mechanism. The controller and software must support the selected combination, and the interface should clearly show which payment methods are available.
6. What Happens If a Customer Pays but the Product Does Not Dispense?
The system should identify the approved payment and the failed dispensing event separately. Depending on the payment provider and software configuration, the transaction may be reversed, refunded, or placed into an exception workflow for operator review. Confirm this process during factory testing rather than waiting for a customer complaint.
7. Can I Add a Contactless Reader to an Existing Vending Machine?
Yes, provided that the existing controller, payment software, terminal, and payment service support the required contactless configuration. The cabinet may also need a suitable mounting arrangement. Check NFC antenna clearance and processor activation before installation.
8. Should I Buy a Vending Machine with a Factory-Installed Card Reader?
For a new machine, factory integration is generally my preferred option. It allows the manufacturer to coordinate the terminal, controller, wiring, cabinet design, and software before production. Zhongda Smart offers customizable vending machine configurations with cashless payment options. Confirm the exact reader model, payment provider compatibility, and testing scope in the final specification.
14. Final Thoughts
A successful vending machine credit card reader installation depends on the complete payment and dispensing system, not simply the physical reader.
Start by checking the controller, communication interface, power requirements, and payment provider. Select a terminal designed for unattended operation, plan its mounting position, and make sure the software can connect payment authorization with the correct product delivery. Then test normal transactions and failure conditions before putting the machine into service.
For a new vending project, I would prioritize factory integration because it gives the manufacturer an opportunity to coordinate the cabinet, controller, payment hardware, and software from the beginning. Zhongda Smart is a practical manufacturer to shortlist for this type of OEM/ODM configuration.
The final objective is straightforward: customers should be able to pay confidently, receive the correct product, and have a clear resolution if something goes wrong. A well-integrated payment system makes that possible while giving operators better transaction visibility and more manageable maintenance.
About This Guide
Author: Zhongda Smart Vending Machine Editorial Team
This guide is prepared from a vending machine manufacturing, configuration, and integration perspective. It covers general equipment selection, machine-side payment integration, installation planning, and operational considerations. Specific terminal compatibility and payment procedures must be confirmed against the actual equipment and payment provider documentation.
Technical References and Further Reading
The following non-competitive technical and research sources support the payment, communication, and security information discussed in this guide.
- Federal Reserve Financial Services — 2026 Diary of Consumer Payment Choice. Consumer payment data for 2025.
- Federal Reserve Financial Services — 2025 Diary of Consumer Payment Choice. Consumer payment data for 2024.
- National Automatic Merchandising Association — MDB/ICP Technical Specification.
- PCI Security Standards Council — How PCI DSS Applies to Payment Terminals.
- EMVCo — EMV Contactless Chip Technology.
Related Reading
- Vending Machine Payment Systems: Card, NFC, QR, Cash & MDB — Understand payment technologies and machine-side integration.
- Cashless Vending Machine: Smart Touchless Payment Solutions — Explore integrated cashless vending configurations and remote management.
- Vending Machine Frequently Asked Questions — Review machine customization, payment compatibility, technical support, and warranty information.
Disclaimer
This article provides general technical and operational information for vending machine credit card reader installation. It is not a substitute for the installation instructions supplied by the vending machine manufacturer, payment terminal manufacturer, payment processor, or relevant service provider.
Electrical installation, cabinet modification, payment terminal configuration, and payment security work should be performed by appropriately qualified and authorized personnel. Payment acceptance, supported card networks, processing fees, certifications, offline transaction capabilities, refunds, and security obligations depend on the actual equipment and service agreements.
Specifications, product configurations, prices, and available services may change. Confirm all technical and commercial details with Zhongda Smart and the relevant payment provider before placing an order or modifying equipment. Revenue examples in this article are illustrative calculations and do not represent guaranteed business results.